Imagine a business owner who has regular customers, steady sales, and a growing market presence. Everything seems to be running smoothly until an unexpected event occurs—a major client delays payment, a key machine breaks down, or seasonal demand suddenly drops.
The business is profitable on paper, but there is one problem: there isn’t enough cash available to cover immediate expenses.
This situation is more common than many entrepreneurs realize. Businesses often focus on increasing revenue while overlooking the importance of maintaining adequate cash reserves. Whether you operate a startup, trading business, manufacturing unit, service company, or freelancer business, maintaining a proper reserve fund is essential for financial stability.
The question is: How much cash should a small business keep in reserve?
The answer depends on several factors, including operating expenses, industry type, business stage, growth plans, and risk exposure. In this guide, we’ll explain practical cash reserve strategies that help businesses remain financially healthy and prepared for unexpected challenges.
Why Cash Reserves Matter for Small Businesses
Many business owners assume profitability automatically means financial security. However, profits and cash availability are not the same.
A company may generate strong sales but still face cash shortages due to:
- Delayed customer payments
- Seasonal business fluctuations
- Unexpected repairs
- Tax liabilities
- GST payments
- Payroll obligations
- Vendor payments
A healthy reserve fund helps businesses:
- Survive temporary revenue declines
- Manage emergencies
- Meet statutory compliance obligations
- Maintain operational continuity
- Avoid expensive borrowing
- Invest in growth opportunities
Strong ACCOUNTING and BOOKKEEPING practices play a critical role in determining the right reserve amount.
Understanding Business Cash Reserves
A cash reserve is money kept aside specifically for future business needs and emergencies.
This amount is separate from:
- Daily operating cash
- Growth investment funds
- Owner withdrawals
- Tax collections
Think of it as a financial safety net that protects your business during uncertain periods.
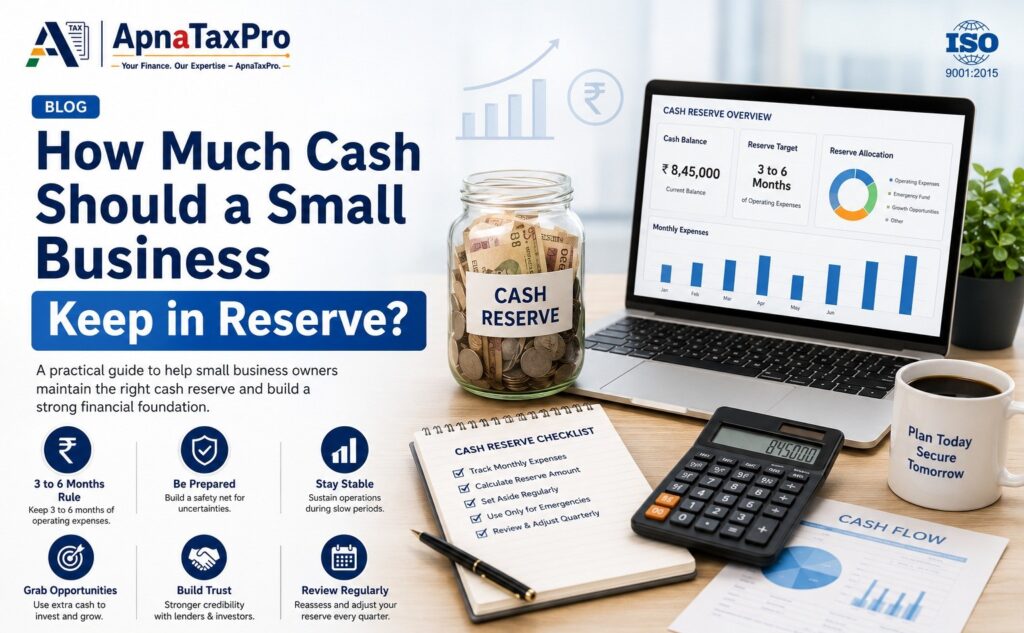
The General Rule: 3 to 6 Months of Operating Expenses
Financial experts generally recommend maintaining enough cash to cover 3–6 months of operating expenses.
Example
Monthly Expenses:
| Expense | Amount |
|---|---|
| Rent | ₹20,000 |
| Salaries | ₹1,20,000 |
| Utilities | ₹10,000 |
| GST & Taxes | ₹15,000 |
| Software & Other Costs | ₹35,000 |
| Total | ₹2,00,000 |
Recommended Cash Reserve:
- 3 Months Reserve = ₹6,00,000
- 6 Months Reserve = ₹12,00,000
For most SMEs and MSMEs, this range provides reasonable protection against temporary financial disruptions.
Factors That Determine Your Ideal Cash Reserve
1. Industry Type
Different industries face different risks.
Low-Risk Businesses
Examples:
- Professional services
- Accounting firms
- Consulting businesses
- Digital agencies
Suggested Reserve:
3–4 months of expenses
Medium-Risk Businesses
Examples:
- Retail stores
- Trading companies
- Distributors
Suggested Reserve:
4–6 months of expenses
High-Risk Businesses
Examples:
- Manufacturing units
- Construction companies
- Infrastructure businesses
Suggested Reserve:
6–12 months of expenses
2. Revenue Stability
Businesses with predictable monthly revenue generally require smaller reserves.
However, businesses dependent on seasonal sales should maintain larger reserves.
Examples:
- Tourism businesses
- Event companies
- Agricultural businesses
- Fashion retailers
These businesses may experience periods with significantly lower income.
3. Customer Payment Cycles
Many SMEs wait 30–90 days to receive payments from customers.
If your business experiences delayed collections, maintaining additional reserves becomes essential.
Good ACCOUNT AND RECORDS management can help monitor receivables and improve cash flow forecasting.
4. Growth Plans
Rapidly growing businesses often require more cash.
Growth may involve:
- Hiring employees
- Purchasing inventory
- Expanding office space
- Marketing investments
- Technology upgrades
Without sufficient reserves, growth can create financial pressure.
Cash Reserve Recommendations by Business Type
| Business Type | Suggested Reserve |
| Freelancer | 3–4 Months |
| Service Provider | 3–6 Months |
| Startup | 6–12 Months |
| Retail Business | 4–6 Months |
| Manufacturing | 6–12 Months |
| Construction Company | 6–12 Months |
| E-commerce Business | 4–6 Months |
Common Mistakes Businesses Make
Keeping Too Little Cash
This can lead to:
- Missed salary payments
- Vendor disputes
- Compliance penalties
- Emergency borrowing
Keeping Too Much Cash
Excessive idle cash may:
- Reduce investment opportunities
- Lower business returns
- Limit expansion potential
The objective is to maintain an optimal balance.
How to Build a Business Cash Reserve
Step 1: Calculate Monthly Operating Expenses
Include:
- Salaries
- Rent
- Utilities
- Professional Tax
- GST obligations
- Loan repayments
- Software subscriptions
- Insurance
Step 2: Set a Target Reserve
Determine whether your business needs:
- 3 months
- 6 months
- 12 months
of operating expenses.
Step 3: Automate Savings
Transfer a fixed percentage of profits into a reserve account every month.
Many successful businesses allocate:
- 5%
- 10%
- 15%
of monthly profits toward reserves.
Step 4: Improve Cash Flow
Effective cash flow management includes:
- Faster invoicing
- Timely collections
- Inventory optimization
- Expense control
- Better supplier negotiations
Professional ACCOUNTING AND financial reporting help identify cash flow improvement opportunities.
The Role of Financial Reporting in Reserve Planning
Without accurate financial reports, determining the correct reserve amount becomes difficult.
Businesses should regularly monitor:
- Profit & Loss Statements
- Balance Sheets
- Cash Flow Statements
- Accounts Receivable Reports
- Accounts Payable Reports
Professional ACCOUNTING SERVICES and BOOKKEEPING SERVICES ensure business owners have access to reliable financial information.
How Compliance Costs Affect Cash Reserve Requirements
Many businesses underestimate statutory obligations.
Examples include:
- GST REGISTRATION compliance
- GST Return Filing
- Income Tax Filing
- TDS payments
- Payroll compliance
- ROC filings
- GUMASTA UDHYAM registration requirements
Maintaining reserves helps businesses avoid penalties resulting from delayed compliance payments.
Why Growing Businesses Need Professional Financial Support
Many entrepreneurs search for:
- ACCOUNTANT OFFICE NEAR ME
- GST FILLING COMPANY
- Accounting Services in Indore
- Bookkeeping Services in Indore
- GST Consultant in Indore
- Tax Consultant in Indore
The reason is simple: professional financial management improves cash visibility and business decision-making.
As businesses grow, managing reserves manually becomes increasingly difficult.
Why Choose ApnaTaxPro
APNA TAX PRO helps startups, SMEs, MSMEs, traders, manufacturers, and service providers make better financial decisions through:
- ACCOUNTING Services
- BOOKKEEPING Services
- Financial Reporting
- GST Registration
- GST Return Filing
- Income Tax Filing
- Payroll Services
- Professional Tax Compliance
- Business Compliance Management
- Virtual CFO Services
- ROC Compliance
- Startup Registration
- Company Registration
- NEW COMPANY REGISTRATION IN INDORE
- MSME Advisory
- Business Advisory
Whether you are looking to improve cash flow, maintain proper account and records, manage working capital, or evaluate growth opportunities among nearby SMEs companies, professional financial guidance can help create a stronger financial foundation.
Frequently Asked Questions (FAQs)
1. How much cash reserve should a startup maintain?
Most startups should maintain at least 6–12 months of operating expenses due to higher business uncertainty.
2. Is three months of cash reserve enough?
For stable service businesses, three months may be sufficient. Higher-risk industries often require more.
3. Should cash reserves be kept in a savings account?
Businesses generally keep reserves in highly liquid accounts that allow quick access during emergencies.
4. How often should cash reserve levels be reviewed?
Review reserves at least quarterly or whenever significant business changes occur.
5. Can a business use a credit line instead of reserves?
Credit lines can help, but relying solely on debt increases financial risk.
6. Do GST and tax liabilities affect reserve planning?
Yes. GST, TDS, income tax, and professional tax obligations should be considered when calculating reserve requirements.
7. What is the difference between working capital and cash reserves?
Working capital supports daily operations, while cash reserves provide protection during unexpected situations.
8. How can bookkeeping improve cash reserve management?
Accurate bookkeeping provides visibility into cash flow, expenses, and future obligations, helping businesses maintain appropriate reserve levels.
Conclusion
Cash reserves are one of the most important financial safeguards for any small business. While every business is different, maintaining 3–6 months of operating expenses is a practical starting point for most SMEs and startups.
The right reserve amount depends on your industry, revenue stability, payment cycles, growth plans, and overall risk profile. Businesses that actively monitor cash flow, maintain accurate accounting records, and plan ahead are better positioned to handle challenges and seize growth opportunities.
Call to Action
Need help improving cash flow, managing business finances, maintaining proper accounting records, or planning financial reserves for your business?
Contact ApnaTaxPro today for expert Accounting Services, Bookkeeping Services, GST Compliance, Virtual CFO Services, Financial Reporting, Business Registration, and Business Advisory support tailored to your business goals.